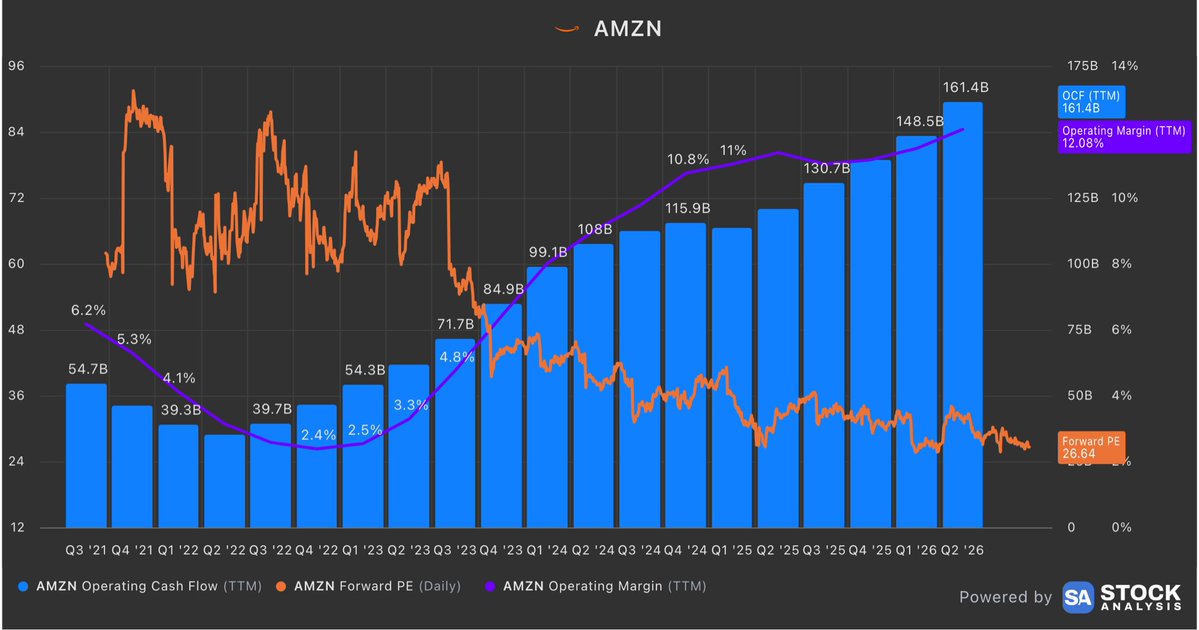
X上的最新讨论围绕亚马逊的估值和基本面展开,有观点称其运营现金流增速、远期市盈率和AWS高毛利业务的组合“很有吸引力”。这一轮话题并非来自新的公司公告,而是对市场对AMZN重新定价的延续性解读。
公开信息显示,亚马逊二季度营收为2006.1亿美元,同比增长19.6%,每股收益5.75美元,显著高于市场预期;AWS收入同比增长37%,为18个季度以来最快增速。与此同时,外部报道还提到AWS积压订单达到4960亿美元,亚马逊今年资本开支计划约2200亿美元,这些数据共同支撑了市场对云业务和AI基础设施投入的关注。
从交易层面看,AMZN仍是本轮讨论的核心标的,原因在于估值、云业务增速和重资本投入三者同时被摆上台面。近期还有多家机构持仓变动类报道出现,显示部分资金继续围绕该股进行配置,但这些动作本身并不改变公司已披露业绩,更多是市场对其增长与回报周期的再评估。
截至目前,已公开可核实的信息仍集中在财报和资本开支预期上,尚无新的公司层面重大公告专门回应这类社交平台观点。
On X, Amazon is back in the spotlight as traders debate whether its valuation still leaves room for upside after a strong quarterly print and sustained AWS momentum. The posts are opinionated, but they are anchored in a real shift in the market’s focus: growth is now being weighed against very large AI and data-center spending.
Amazon reported second-quarter revenue of $200.61 billion, up 19.6% year over year, and earnings per share of $5.75. AWS revenue rose 37% year over year, the fastest pace in 18 quarters, while outside reports also put AWS backlog at $496 billion and Amazon’s 2026 capex plan at about $220 billion.
That combination keeps AMZN at the center of the debate. Bulls point to high-margin AWS revenue and accelerating demand, while skeptics focus on whether the return on the company’s heavy infrastructure buildout will be timely enough to justify the spend.
Recent stockholder-filing headlines showing new purchases by several institutions suggest some investors are still adding exposure, but those filings are secondary to the broader narrative: Amazon’s operating results and capital intensity remain the main drivers of the shares.